The setup: record index, yellow signal, narrow leadership
This issue does not start with neoclouds. It starts with the tape. The S&P 500 closed at a new record on Thursday, the Nasdaq also advanced and the Dow was only slightly positive. Through Thursday, the S&P 500 and Nasdaq were modestly higher for the week while the Dow lagged. That is not a broken tape, but it is not a market carrying everything either.
The WickedDesk market signal stands at 69 on Friday morning, yellow. The process stays selective: new longs need a strong catalyst, a strong group and real volume. That matches the week. AI, software, memory and selected special situations were bought. At the same time, earnings reactions were strict when margins, guidance or follow-through did not confirm.
Neoclouds are the focus, but not the entire issue. The more important thread is this: capital is looking for AI infrastructure and compute capacity, yet it is sorting the theme aggressively. NBIS leads. IREN improves after operational acceptance. CRWV proves demand, but remains a watch chart. HUT, RIOT, CIFR and WULF have large contracts or infrastructure stories, but price does not confirm cleanly. That separation is more useful for next week's preparation than the AI headline alone.
Week path: inflation helped, earnings sorted hard
Monday opened with caution ahead of CPI, PPI and retail sales. Oil and Iran headlines kept the macro frame tense, while selected tech and AI names stayed in demand. Wednesday brought CPI relief. Thursday brought a lower than expected PPI reading. Yields eased for parts of the session and the S&P 500 reached a new high.
Friday was not fully complete at the data cutoff. Retail sales and the University of Michigan consumer sentiment survey were still the last major macro checks of the week. The weekly read therefore stays open: inflation helped the market, but the consumer check decides whether the move broadens or stays concentrated in AI, software and a few special groups.
Earnings were the second filter. CoreWeave confirmed demand for AI compute. Cisco showed strong AI orders, but the stock sold off on margin and outlook concerns. Applied Materials reported solid numbers and still traded lower after hours. Memory and storage names acted better. The message for traders is clear: AI is not a free pass. The reaction matters, not the headline.
| Event | Day | Read |
|---|---|---|
| Start ahead of CPI, PPI and retail sales | Mon | Index caution, continued interest in AI infrastructure |
| CPI cools inflation concern | Wed | Yields and the Fed path become negotiable again |
| PPI below expectations, S&P 500 record | Thu | Index strong, earnings reactions still selective |
| Retail sales and sentiment still open | Fri | Follow-up check for breadth, consumer and risk-on |
- Start ahead of CPI, PPI and retail sales
- Day
- Mon
- Read
- Index caution, continued interest in AI infrastructure
- CPI cools inflation concern
- Day
- Wed
- Read
- Yields and the Fed path become negotiable again
- PPI below expectations, S&P 500 record
- Day
- Thu
- Read
- Index strong, earnings reactions still selective
- Retail sales and sentiment still open
- Day
- Fri
- Read
- Follow-up check for breadth, consumer and risk-on
Market signal: yellow 69, not a green light
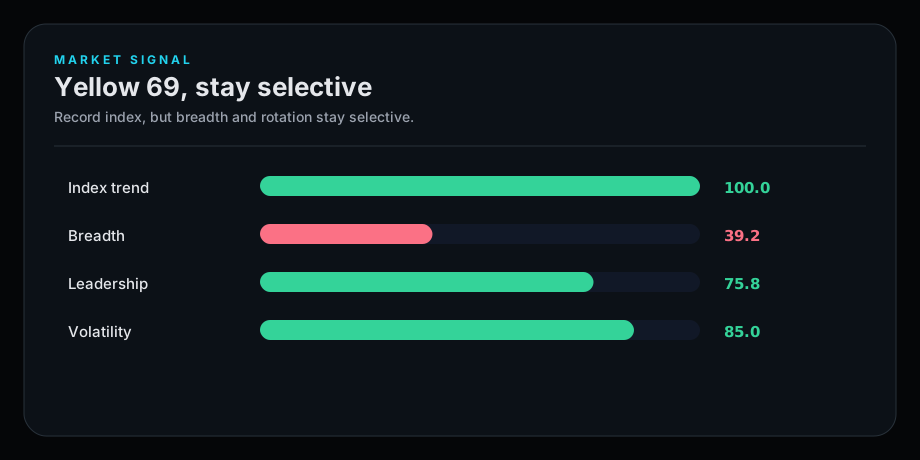
The current WickedDesk snapshot shows yellow at 69. That is enough to work on leaders, but not enough for blanket risk. The stance remains selective: catalyst, group and volume must fit together. The distinction matters. A yellow tape allows NBIS, DELL or selected software setups. It does not allow buying every former miner because it now says AI infrastructure.
Group leadership confirms that read. Financials rank first, technology second, cyclicals third, health care fourth. Technology has the stronger four-week move at +6.1%, but financials lead the current sector rank. This is not a one-sided tech bull market. It is a selective market with several pockets of strength.
| Read | Value | Pillar |
|---|---|---|
| The index carries, but that alone is not enough | 100.0 | Index trend |
| Participation is too narrow for a green light | 39.2 | Breadth |
| Leaders exist, but selectively | 75.8 | Leadership |
| VIX backdrop remains controlled | 85.0 | Volatility |
- The index carries, but that alone is not enough
- Value
- 100.0
- Pillar
- Index trend
- Participation is too narrow for a green light
- Value
- 39.2
- Pillar
- Breadth
- Leaders exist, but selectively
- Value
- 75.8
- Pillar
- Leadership
- VIX backdrop remains controlled
- Value
- 85.0
- Pillar
- Volatility
Rotation: financials lead, technology remains the stronger engine
The sector rank is less obvious than the AI tape suggests. Financials lead the current snapshot at rank 1. Technology sits at rank 2, but has the stronger four-week move. Cyclicals, health care, materials and energy follow closely. That produces a yellow read: strength exists, but breadth is not unified.
For preparation, the order matters. First check which group actually leads. Then sort stocks inside that group by RS, distance to high and volume. Only then look for the setup in Atlas. If you start with the theme and finish with the chart, leadership appears. If you start with the story, you can easily end up with weak confirmation.
| Group | Rank | Leaders | One Week | 4 weeks |
|---|---|---|---|---|
| Financials | 1 | UMAC, PMTS, OPHC, ENVA | +0.1% | +3.9% |
| Technology | 2 | QMCO, BLZE, APPS, DELL | 0.0% | +6.1% |
| Consumer cyclical | 3 | RRGB, FGI, LVLU, LIND | +0.2% | +4.1% |
| Health care | 4 | AGL, QTTB, OTLK, REPL | +0.4% | +3.8% |
| Materials | 5 | GORO, FRD, LWLG, MTRN | 0.0% | +6.5% |
| Energy | 6 | FTK, PBF, FET, CLMT | +0.3% | +6.0% |
- Financials
- Rank
- 1
- One Week
- +0.1%
- 4 weeks
- +3.9%
- Technology
- Rank
- 2
- One Week
- 0.0%
- 4 weeks
- +6.1%
- Consumer cyclical
- Rank
- 3
- One Week
- +0.2%
- 4 weeks
- +4.1%
- Health care
- Rank
- 4
- One Week
- +0.4%
- 4 weeks
- +3.8%
- Materials
- Rank
- 5
- One Week
- 0.0%
- 4 weeks
- +6.5%
- Energy
- Rank
- 6
- One Week
- +0.3%
- 4 weeks
- +6.0%
Earnings: AI is being paid for, but not every beat is enough
CoreWeave was the cleanest fundamental catalyst of the week. The company reported $2.575 billion in quarterly revenue, 112% growth and roughly $104 billion of revenue backlog. That proves real demand for AI compute. Capital intensity remains high, so the chart does not automatically become a leader. It has to turn the earnings reaction into a second base.
Cisco showed the other side. AI infrastructure orders reached $9.3 billion for the fiscal year, revenue and earnings were strong, but the stock fell after results. Investors focused on margins and outlook. Applied Materials also posted solid numbers, but traded lower after hours. Memory and storage names such as Sandisk, Micron and Seagate acted better. The week confirms: AI is not a free pass. The reaction decides, not the headline.
| Event | Read | Stock |
|---|---|---|
| Q2 revenue $2.575B, backlog around $104B | Demand confirmed, chart remains watch | CRWV |
| AI orders $9.3B for the fiscal year | Beat is not enough if margins or outlook weigh | CSCO |
| Strong numbers, weak after-hours reaction | Semis need follow-through | AMAT |
| Memory and storage in demand | AI infrastructure also rotates into suppliers | SNDK/MU/STX |
- Q2 revenue $2.575B, backlog around $104B
- Read
- Demand confirmed, chart remains watch
- Stock
- CRWV
- AI orders $9.3B for the fiscal year
- Read
- Beat is not enough if margins or outlook weigh
- Stock
- CSCO
- Strong numbers, weak after-hours reaction
- Read
- Semis need follow-through
- Stock
- AMAT
- Memory and storage in demand
- Read
- AI infrastructure also rotates into suppliers
- Stock
- SNDK/MU/STX
Theme radar: cloud leads, steel and cybersecurity join
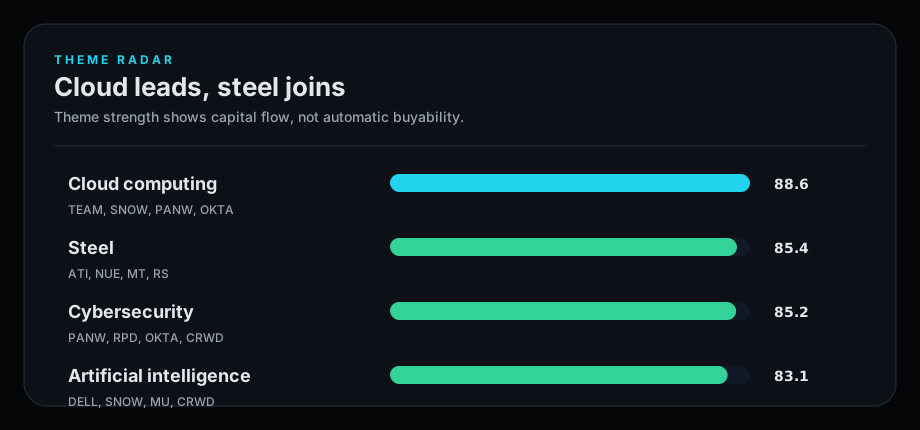
In the live theme ranking from August 14, cloud computing leads with a strength score of 88.6. Steel follows at 85.4, cybersecurity at 85.2 and artificial intelligence at 83.1. The AI infrastructure complex remains in the right part of the tape, but it is not the only active capital flow. Steel and cybersecurity show that leadership has to be sorted more broadly than neoclouds alone.
This week is the clean example. NBIS has RS 98 and clear momentum confirmation. IREN has operating news but still sits far below its high. HUT has large contract numbers but falls in the short window. If you buy only the theme, you miss the spread. If you sort the stocks inside the theme, leadership appears faster.
| Theme | Rank | Read | Leaders | Strength |
|---|---|---|---|---|
| Cloud computing | 1 | Cloud leads, neoclouds are only one part of it | TEAM, SNOW, PANW, OKTA | 88.6 |
| Steel | 2 | Industrial cyclicals are working too | ATI, NUE, MT, RS | 85.4 |
| Cybersecurity | 3 | Software infrastructure remains liquid leadership | PANW, RPD, OKTA, CRWD | 85.2 |
| Artificial intelligence | 4 | AI remains strong, not every AI name leads | DELL, SNOW, MU, CRWD | 83.1 |
- Cloud computing
- Rank
- 1
- Read
- Cloud leads, neoclouds are only one part of it
- Strength
- 88.6
- Steel
- Rank
- 2
- Read
- Industrial cyclicals are working too
- Strength
- 85.4
- Cybersecurity
- Rank
- 3
- Read
- Software infrastructure remains liquid leadership
- Strength
- 85.2
- Artificial intelligence
- Rank
- 4
- Read
- AI remains strong, not every AI name leads
- Strength
- 83.1
Neocloud comparison: one basket, three states
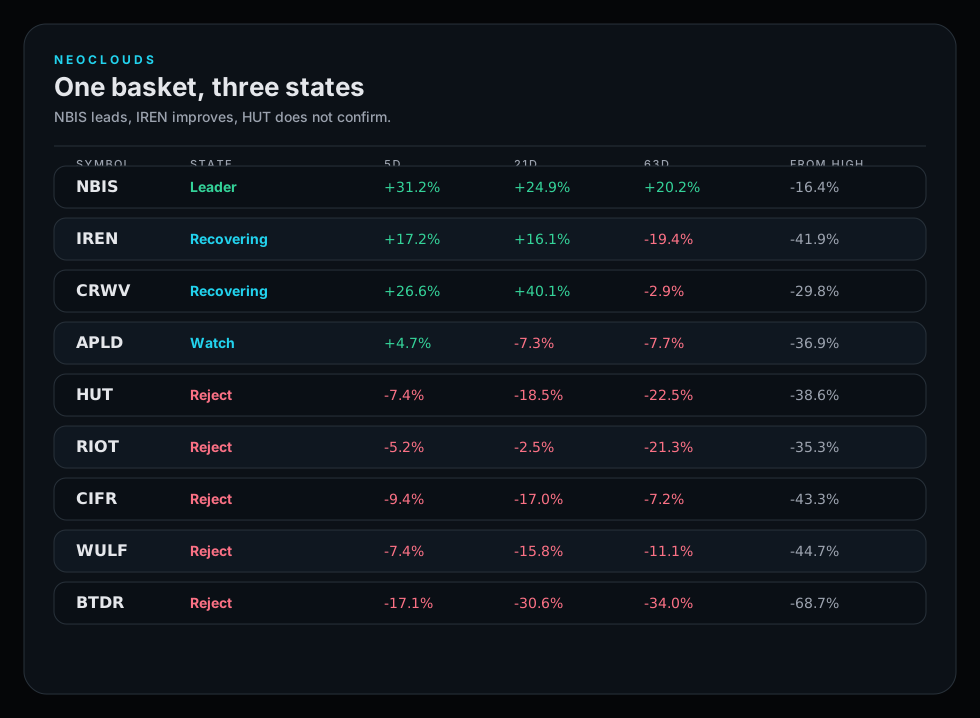
The basket splits into three states. NBIS is the leader. IREN and CRWV are recovering names with strong news. APLD is an infrastructure watch because the CoreWeave leases are real, but price does not lead yet. HUT, RIOT, CORZ, CIFR, BTDR and WULF show that the miner and power side has not confirmed cleanly yet. Price data is clear: NBIS is up 31.2% over five trading days and 20.2% over 63 trading days. IREN is up 17.2% over five days, but still down 19.4% over 63 days. HUT is down 7.4% over five days and 22.5% over 63 days.
That is the core of the focus: sharing the same headline is not enough. Leaders lead across multiple windows. Recovering names must prove the first reaction holds. Weak names stay out, even when the press release sounds large.
| Symbol | RS | State | Five Days | From High | Twenty One Days | Sixty Three Days |
|---|---|---|---|---|---|---|
| NBIS | 98 | Leader | +31.2% | -16.4% | +24.9% | +20.2% |
| IREN | 84 | Recovering | +17.2% | -41.9% | +16.1% | -19.4% |
| CRWV | 58 | Recovering | +26.6% | -29.8% | +40.1% | -2.9% |
| APLD | 66 | Watch | +4.7% | -36.9% | -7.3% | -7.7% |
| HUT | 94 | Reject | -7.4% | -38.6% | -18.5% | -22.5% |
| RIOT | 64 | Reject | -5.2% | -35.3% | -2.5% | -21.3% |
| CIFR | 91 | Reject | -9.4% | -43.3% | -17.0% | -7.2% |
| WULF | 84 | Reject | -7.4% | -44.7% | -15.8% | -11.1% |
| BTDR | 9 | Reject | -17.1% | -68.7% | -30.6% | -34.0% |
- RS
- 98
- State
- Leader
- Five Days
- +31.2%
- From High
- -16.4%
- Twenty One Days
- +24.9%
- Sixty Three Days
- +20.2%
- RS
- 84
- State
- Recovering
- Five Days
- +17.2%
- From High
- -41.9%
- Twenty One Days
- +16.1%
- Sixty Three Days
- -19.4%
- RS
- 58
- State
- Recovering
- Five Days
- +26.6%
- From High
- -29.8%
- Twenty One Days
- +40.1%
- Sixty Three Days
- -2.9%
- RS
- 66
- State
- Watch
- Five Days
- +4.7%
- From High
- -36.9%
- Twenty One Days
- -7.3%
- Sixty Three Days
- -7.7%
- RS
- 94
- State
- Reject
- Five Days
- -7.4%
- From High
- -38.6%
- Twenty One Days
- -18.5%
- Sixty Three Days
- -22.5%
- RS
- 64
- State
- Reject
- Five Days
- -5.2%
- From High
- -35.3%
- Twenty One Days
- -2.5%
- Sixty Three Days
- -21.3%
- RS
- 91
- State
- Reject
- Five Days
- -9.4%
- From High
- -43.3%
- Twenty One Days
- -17.0%
- Sixty Three Days
- -7.2%
- RS
- 84
- State
- Reject
- Five Days
- -7.4%
- From High
- -44.7%
- Twenty One Days
- -15.8%
- Sixty Three Days
- -11.1%
- RS
- 9
- State
- Reject
- Five Days
- -17.1%
- From High
- -68.7%
- Twenty One Days
- -30.6%
- Sixty Three Days
- -34.0%
Atlas study NBIS: demand is visible in price
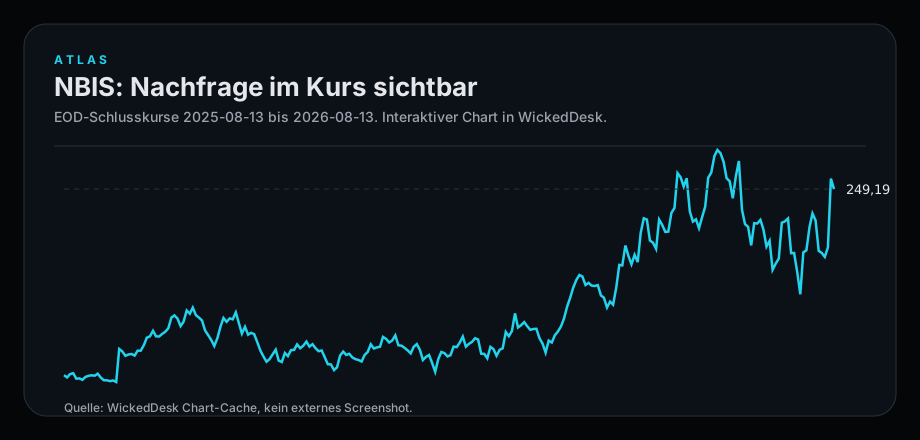
Nebius is the cleanest public neocloud expression of the week. The company reports $575 million of AI cloud revenue, 514% growth, $3.0 billion ARR and roughly 50% adjusted EBITDA margin in AI cloud. It also closed four landmark deals above $1 billion average contract value and customer prepayments were part of a large portion of closed deals in the quarter.
The chart confirms the report. In WickedDesk, NBIS carries RS 98, setup score 100, 45.9% one-month momentum and 179.3% over six months. Despite the day loss, the stock is only 16.4% below its high while many peers sit 30 to 70% below theirs. NBIS remains the reference leader as long as pullbacks above the last breakout zone get bought. Do not chase after +31% in five days. A tight flag or controlled reclaim is needed for a new setup.
Atlas study IREN: acceptance beats announcement
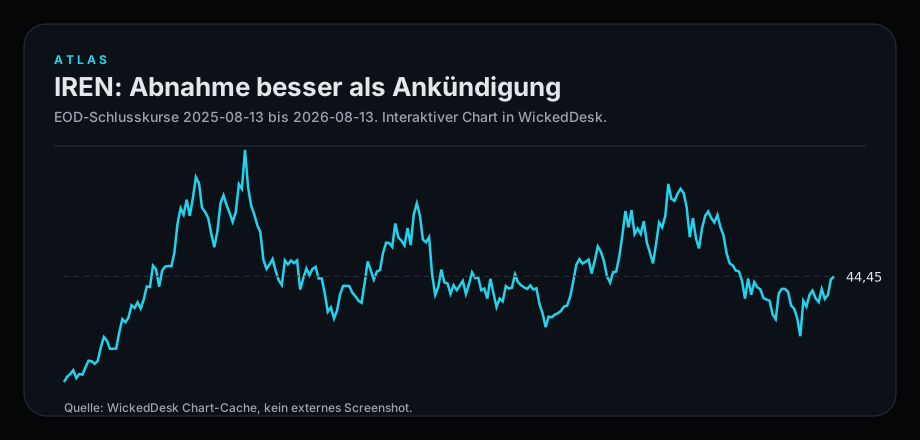
IREN delivered the most important operating milestone inside the basket. Horizon 1 was delivered to and accepted by Microsoft. IREN also achieved NVIDIA Exemplar Cloud status for GB300 NVL72. Horizon 1 is the first of four 50 MW IT load deployments for Microsoft in 2026 under a five-year $9.7 billion cloud services contract.
The chart has improved, but it is not clean yet. IREN is up 17.2% over five trading days and 16.1% over 21 trading days. At the same time the stock remains 41.9% below its high and still down 19.4% over 63 trading days. This is a watch setup, not a confirmed leader. If IREN holds the reaction after Microsoft acceptance and builds a first higher base above it, the name becomes more interesting. If it falls back into the old range, it was only a news pop.
HUT: the large contract story is not being paid
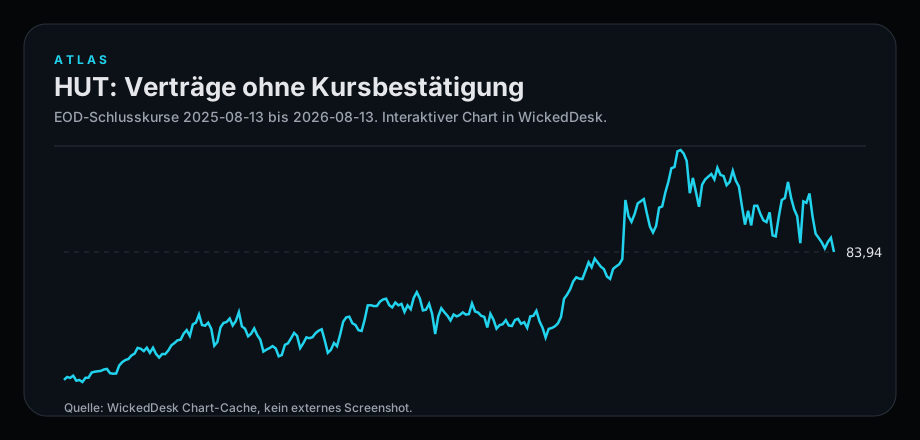
Hut 8 is the countercheck to the enthusiasm. The company points to 949 MW of contracted AI data center capacity, 1,330 MW of supporting utility capacity, $26.6 billion of expected base-term contract value and more than $1.75 billion of expected average annual NOI. Hut 8 also points to $7.5 billion of secured project financing.
Price still says no. HUT is down 7.7% on the day in the snapshot, down 7.4% over five trading days, down 18.5% over 21 trading days and 38.6% below its high. That does not fit a leader. The correct read is not to ignore the story. The correct read is to park the story until price builds a first higher base and clear relative strength against NBIS and IREN.
Infrastructure layer: the market is not buying every megawatt
RIOT, WULF, CIFR and APLD show how wide the neocloud complex has become. Riot brings 191 MW of critical IT capacity and $9.1 billion of base-term contract value into the discussion through its Anthropic agreement. TeraWulf points to roughly 401 MW of critical IT load and about $19 billion of contracted revenue with Anthropic. Cipher highlights earlier Black Pearl capacity delivery. Applied Digital is linked to CoreWeave through 400 MW at Polaris Forge 1 and roughly $11 billion of expected lease revenue.
Price data is stricter than contract data. RIOT sits at RS 64 in the WickedDesk snapshot, 35.3% below its high and down 21.3% over three months. WULF is 44.7% below its high. CIFR has RS 91, but is down 7.8% on the day and 43.3% below its high. APLD has real lease structure, but RS 66 and a 36.9% distance from the high. Infrastructure is the story, not automatically the setup.
| Symbol | Event | Evidence | Price Read |
|---|---|---|---|
| RIOT | Anthropic agreement | 191 MW, $9.1B base value | RS 64, 35.3% below high |
| WULF | Anthropic lease | 401 MW, about $19B | RS 84, 44.7% below high |
| CIFR | Black Pearl | capacity delivered early | RS 91, weak day move |
| APLD | CoreWeave leases | 400 MW, about $11B | RS 66, not a leader yet |
- Event
- Anthropic agreement
- Evidence
- 191 MW, $9.1B base value
- Price Read
- RS 64, 35.3% below high
- Event
- Anthropic lease
- Evidence
- 401 MW, about $19B
- Price Read
- RS 84, 44.7% below high
- Event
- Black Pearl
- Evidence
- capacity delivered early
- Price Read
- RS 91, weak day move
- Event
- CoreWeave leases
- Evidence
- 400 MW, about $11B
- Price Read
- RS 66, not a leader yet
Peer check: CRWV improves, miners stay heavy
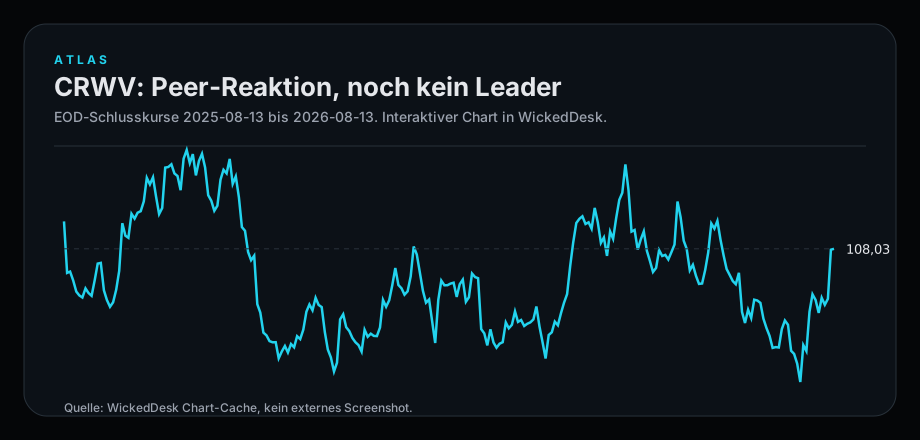
CoreWeave and the mining pivots are mixed. CRWV has the strongest peer reaction after NBIS: +26.6% over five trading days and +40.1% over 21 trading days. But RS is only 58 and the stock remains 29.8% below its high. It is not a quality leader yet, but it belongs on a second-base watch.
The harder message comes from CORZ, CIFR, BTDR and WULF. CORZ is down 12.9% over 21 trading days, CIFR down 17.0%, BTDR down 30.6%, WULF down 15.8%. The miner and power transformation gets bought on isolated days, but the basket is not carried consistently yet. As long as that remains true, leadership belongs to AI cloud providers with confirmed revenue or accepted capacity, not to the broad former-miner group.
| Symbol | RS | State | Five Days | From High | Twenty One Days |
|---|---|---|---|---|---|
| CRWV | 58 | Watch | +26.6% | -29.8% | +40.1% |
| CORZ | 39 | Reject | -6.0% | -34.4% | -12.9% |
| CIFR | 91 | Reject | -9.4% | -43.3% | -17.0% |
| WULF | 84 | Reject | -7.4% | -44.7% | -15.8% |
- RS
- 58
- State
- Watch
- Five Days
- +26.6%
- From High
- -29.8%
- Twenty One Days
- +40.1%
- RS
- 39
- State
- Reject
- Five Days
- -6.0%
- From High
- -34.4%
- Twenty One Days
- -12.9%
- RS
- 91
- State
- Reject
- Five Days
- -9.4%
- From High
- -43.3%
- Twenty One Days
- -17.0%
- RS
- 84
- State
- Reject
- Five Days
- -7.4%
- From High
- -44.7%
- Twenty One Days
- -15.8%
Private benchmarks: Lambda, Crusoe and Fluidstack set the bar
Public stocks tell only part of the neocloud story. Lambda closed a $1.0 billion credit facility to expand NVIDIA infrastructure and data center capacity. Crusoe points to roughly 4.9 GW of contracted AI infrastructure capacity across data centers and cloud. Fluidstack appears as a financing and development partner in large Anthropic and infrastructure projects.
That is useful for the public watchlist. If private providers finance at gigawatt scale, a press release is not enough for listed names. The market wants delivery, customer prepayments, durable financing and stable relative strength. Only then does capacity become a tradable stock.
Workflow: week first, theme second, stock third
The clean order for next week is: market signal and week path first, rotation second, theme third, stock fourth, Atlas last. This issue shows why. If you only read neoclouds, you miss financials, memory, software, retail data and the yellow regime filter. If you only read the index, you miss the spread inside the AI infrastructure basket.
The practical flow: cloud computing and artificial intelligence stay on the theme list. Inside the neocloud basket, NBIS gets measured against IREN, CRWV, APLD, HUT and RIOT. NBIS needs rest after the expansion. IREN needs a first higher base after Microsoft acceptance. CRWV needs a second base after the earnings reaction. APLD has to show that the CoreWeave leases are arriving in price. HUT and RIOT need price confirmation at all.
Next week: follow-up checks before chasing a new story
Next week has a clear calendar. Monday, August 17, brings the Empire State Manufacturing Index. Tuesday brings housing starts, building permits, industrial production and capacity utilization. Wednesday, August 19, brings the FOMC minutes. Thursday brings the Philadelphia Fed Index and Leading Indicators. Friday is quieter in the U.S., while Canada and the U.K. publish retail sales. The larger Fed event is one week later: Jackson Hole runs from August 27 to 29.
The next issue therefore has concrete follow-up checks. First, the market has to confirm the yellow signal after retail sales, housing data and FOMC minutes. Second, retail earnings from Home Depot, Lowe's, Target, TJX and Walmart have to show whether the consumer supports index strength or only a few mega-caps are carrying the tape. Third, memory, software and AI hardware have to hold the reaction after Cisco, Applied Materials and the storage movers. Fourth, NBIS needs a tight flag or clean digestion of the move. IREN and CRWV need higher bases while HUT, RIOT, CIFR and WULF continue to lag.
If those checks improve, the watchlist can widen. If not, the work stays narrow: only leaders, only liquid names, only setups with real relative strength.
| Event | Date | Follow up |
|---|---|---|
| Empire State Manufacturing | Aug 17 | Industry and risk appetite before housing data |
| Housing starts, building permits, industrial production | Aug 18 | Rates, builders, industrials and cyclicals |
| FOMC minutes | Aug 19 | Does the Fed confirm the yellow filter or ease rate pressure? |
| Philadelphia Fed, Leading Indicators, retail earnings | Aug 20 | Breadth, consumer and cyclical groups |
| Jackson Hole | Aug 27 to 29 | Prepare Fed communication for issue 010 |
- Empire State Manufacturing
- Date
- Aug 17
- Follow up
- Industry and risk appetite before housing data
- Housing starts, building permits, industrial production
- Date
- Aug 18
- Follow up
- Rates, builders, industrials and cyclicals
- FOMC minutes
- Date
- Aug 19
- Follow up
- Does the Fed confirm the yellow filter or ease rate pressure?
- Philadelphia Fed, Leading Indicators, retail earnings
- Date
- Aug 20
- Follow up
- Breadth, consumer and cyclical groups
- Jackson Hole
- Date
- Aug 27 to 29
- Follow up
- Prepare Fed communication for issue 010
Follow-up from issue 008
Issue 008 promised a follow-up on breadth and leadership groups. The current data confirms the selective read. The market signal is yellow at 69, the index side is strong and breadth is not enough for blanket risk-on. In the sector ranking, financials lead technology. In the theme ranking, cloud computing, cybersecurity and artificial intelligence remain strong.
The answer for issue 009 is therefore: not the whole AI basket leads. NBIS carries neocloud leadership. IREN has to build a base after operating confirmation. CRWV has to convert the earnings reaction into a second base. APLD, HUT, RIOT, CIFR and WULF have infrastructure events, but not clean leadership yet. That is the check for issue 010.
Watchlist of the week
The list is intentionally short. The point is not to collect every AI name, but to keep the hierarchy by week, group, stock and setup clear.
| Symbol | Risk | Role | Condition |
|---|---|---|---|
| NBIS | Do not chase after +31% in five days | Leader | Tight flag or controlled reclaim after the jump |
| IREN | Still 41.9% below high | Watch | First higher base after Microsoft acceptance |
| CRWV | RS 58, not a quality leader yet | Watch | Second base after +40% in 21 days |
| APLD | RS 66, 36.9% below high | Infrastructure watch | Lease story must confirm through RS and distance to high |
| RIOT | RS 64, below the 50-day line | Reject until confirmation | Anthropic agreement must turn into relative strength |
| HUT | Contract story without price confirmation | Reject until confirmation | Relative strength against NBIS and IREN plus higher base |
- Risk
- Do not chase after +31% in five days
- Role
- Leader
- Condition
- Tight flag or controlled reclaim after the jump
- Risk
- Still 41.9% below high
- Role
- Watch
- Condition
- First higher base after Microsoft acceptance
- Risk
- RS 58, not a quality leader yet
- Role
- Watch
- Condition
- Second base after +40% in 21 days
- Risk
- RS 66, 36.9% below high
- Role
- Infrastructure watch
- Condition
- Lease story must confirm through RS and distance to high
- Risk
- RS 64, below the 50-day line
- Role
- Reject until confirmation
- Condition
- Anthropic agreement must turn into relative strength
- Risk
- Contract story without price confirmation
- Role
- Reject until confirmation
Methodology and limits
Internal market and group data come from the WickedDesk snapshot dated August 14, 2026. The neocloud price and scanner values come from the stored WickedDesk snapshot for this issue. External fundamental data comes from primary sources from Nebius, IREN, CoreWeave, Riot, TeraWulf, Cipher, Applied Digital, Lambda, Crusoe and Hut 8, plus checked market reports on CPI, PPI, retail sales, Cisco, Applied Materials and memory stocks. ARR, contract value, capacity and customer prepayments are company-provided figures and not guaranteed revenue.
This issue is not investment advice. It is a working document for the WickedDesk process: check the market, read rotation, frame the theme, test the leader, wait for the setup and reject weak names even when the story sounds good.